Quick answer: Homes in Roscoe Village and North Center range from 1890s frame cottages to brick two-flats to large new builds, so the right policy depends on the house. Most homeowners here should insure to full rebuilding cost, add water backup coverage for the basement, check how older wiring, plumbing, and roofs affect their quote, and use the right policy for a two-flat. An independent agent can compare carriers that handle older and renovated Chicago homes differently.
Our office on Damen Avenue in Bucktown is a short drive straight up Damen from Roscoe Village and North Center, and we insure plenty of homes there. Families move in for the schools, the parks, and the shops along Roscoe Street and Lincoln Avenue, and they often renovate or add on soon after. That mix of old and new is exactly what makes insurance here worth a careful look.
What Makes Roscoe Village and North Center Different
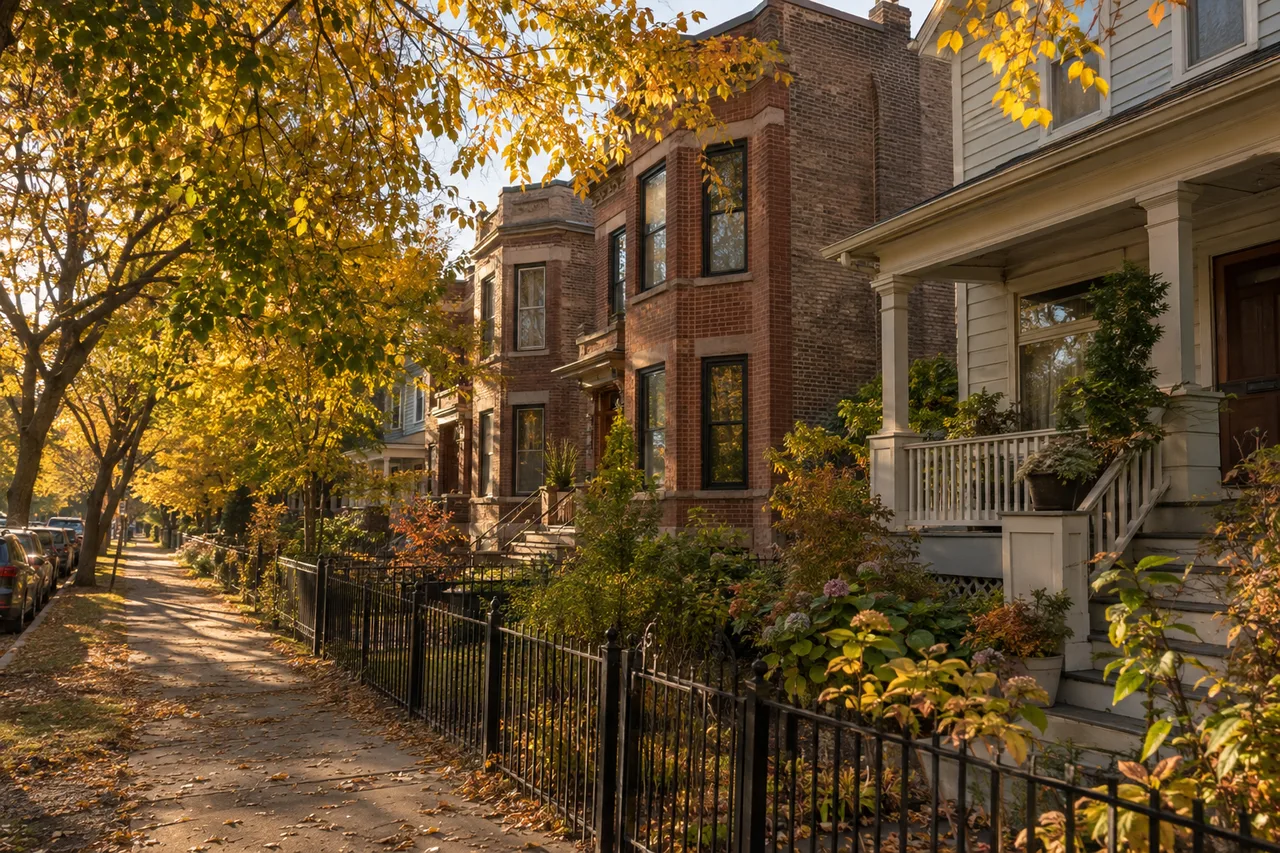
- Frame cottages and workers' homes. Many blocks still have late 19th and early 20th century wood frame houses, often raised and expanded over the years. Frame construction and older systems can affect both price and which carriers will write the policy.
- Brick two-flats and greystones. Plenty of owners live in one unit and rent the other, which calls for a policy built for two units.
- Big renovations and new construction. Gut rehabs, second-story additions, and new single-family homes push rebuilding costs well above what a quick online quote assumes.
- Finished basements. Basements here are often family rooms, offices, and guest suites, which raises the stakes of any water backup.
- The North Branch of the Chicago River. Blocks on the west side of North Center near the river and Horner Park sit closer to the water than most of the North Side.
Coverage Considerations for Local Homes
Insure to rebuilding cost, not market value
Your dwelling limit should reflect what it would cost to rebuild your home with similar materials and finishes, not what it would sell for. Custom millwork, high-end kitchens, and additions all raise that number. Ask about extended or guaranteed replacement cost, and read our guide on whether your home is underinsured.
Ordinance or law coverage
If an older home is badly damaged, the City of Chicago building code may require upgrades to wiring, plumbing, or structure during the rebuild. Standard policies include only a small amount for these costs. Owners of older frame homes and two-flats should consider a higher ordinance or law limit.
Water backup and flood
Sewer and drain backup is excluded from standard policies and has to be added by endorsement. After heavy summer storms, basement backups are some of the most common claims we see on the North Side. Flood from rising water is a separate exclusion and requires its own policy. Our guides to sump pump and sewer backup coverage and basement water damage explain the difference.
Service lines
Many homes here still have original water and sewer lines running to the street. Repairs can mean digging up the parkway, and that is not covered by a standard policy. Service line coverage is an affordable add-on that fills the gap.
Two-flats and rental units
If you live in one unit and rent the other, you need a policy written for an owner-occupied two-unit building, with loss of rents coverage if a fire or major leak forces your tenant out. If you move out and rent both units, the policy needs to change. Our Chicago two-flat insurance guide covers both setups.
Auto Insurance for Roscoe Village and North Center Drivers
Street parking, alley garages, and busy corridors like Western, Lincoln, Irving Park, and Addison all play into auto insurance here. Comprehensive coverage matters for parked cars exposed to theft, break-ins, falling branches, and hail. Our new guide to comprehensive vs. collision coverage in Chicago walks through when each is worth it, and bundling your car with your home through a home and auto bundle usually brings the biggest discount.
Renters in Roscoe Village and North Center
Many renters here live in two-flats and three-flats where the landlord's policy covers the building, not your things. Renters insurance covers your belongings, your liability, and a hotel if your unit becomes unlivable, usually for a modest monthly cost. See our Chicago renters insurance guide.
A Few Local Things That Surprise People
- Detached garages off the alley are covered under other structures, usually at 10% of your dwelling limit, which may be too little for a new garage with a rooftop deck.
- Bikes, strollers, and gear stolen from a garage or porch are covered under personal property, subject to your deductible.
- Hosting block parties and kids' birthday parties is common here, and a personal umbrella policy adds liability protection beyond your home and auto limits.
- Older roofs may be settled at actual cash value, so check your policy before winter. Our article on ice dam damage and home insurance explains why.
Your Roscoe Village and North Center Insurance Checklist
- Confirm your dwelling limit reflects today's rebuilding cost, including renovations.
- Add water backup coverage with a limit that matches your finished basement.
- Check FEMA flood maps if you live near the North Branch of the Chicago River.
- Raise ordinance or law coverage on older frame homes and two-flats.
- Consider service line coverage for original water and sewer lines.
- Make sure a two-flat is insured as a two-unit, owner-occupied building.
- Check your detached garage limit under other structures.
- Bundle home and auto, and ask about a personal umbrella.
The Bottom Line
Roscoe Village and North Center homes are as varied as the people who live in them, and the right policy for a renovated greystone is not the right one for a frame cottage or a two-flat. If you are buying here, our first-time home buyer insurance guide is a good place to start, and our Bucktown home insurance guide covers the neighborhood just south.
As an independent insurance agency in Chicago, we compare homeowners insurance and car insurance from multiple carriers for North Side homeowners. Contact Six Corners Insurance for a free quote.
Sources
- Illinois Department of Insurance — Homeowner and Renter Shopping Tips
- Illinois Department of Insurance — Shopping for Homeowners Insurance (PDF)
- National Association of Insurance Commissioners — Homeowners Insurance
- FloodSmart (National Flood Insurance Program) — Eligibility
- City of Chicago — Blocking Rainwater and Preventing Sewer Backup
Frequently Asked Questions
How much is home insurance in Roscoe Village and North Center?
It depends on the home more than the zip code: rebuilding cost, age of the roof, wiring and plumbing, claims history, deductible, and add-ons like water backup coverage. Older frame homes and larger renovated houses often cost more to insure because they cost more to rebuild. The best way to know is to compare quotes from several carriers.
Do I need water backup coverage in North Center?
If you have a basement, especially a finished one, we strongly recommend it. Standard homeowners policies exclude sewer and drain backup, and heavy summer storms can overwhelm Chicago’s combined sewer system across the North Side. Water backup coverage is an inexpensive endorsement that can save thousands.
Does homeowners insurance cover flooding from the Chicago River?
No. Standard homeowners policies exclude flood. Homes near the North Branch of the Chicago River or in low-lying blocks should check FEMA flood maps and consider a flood policy from the National Flood Insurance Program or a private carrier.
How should I insure a two-flat in Roscoe Village?
If you live in one unit and rent the other, you usually need an owner-occupied policy written for a two-unit building, with liability that covers your tenants’ use of the property. If you do not live there, you need a landlord or dwelling fire policy. Your tenants should carry their own renters insurance.
Does my policy cover my renovation or addition?
Not automatically. Tell your agent before a major renovation, since your dwelling limit may need to rise and some carriers want to know about vacancy or work in progress. Make sure your contractor carries liability and workers’ compensation insurance.